Ireland's leading loss assessor
Subsidence damage insurance claims
Subsidence is one of the most complicated home insurance claims you can face, and the difference between a fair settlement and a poor one often comes down to the quality of the evidence and who is managing the process. We handle your subsidence claim from start to finish, bringing in the right reports, pushing back where the insurer’s assessment falls short, and negotiating to get the outcome your property needs.
Annual claim instructions
Nationwide response
Ireland’s largest loss assessors
Combined industry experience
Why customers choose us in their moment of need
Immediate Support
What to do immediately after discovering subsidence
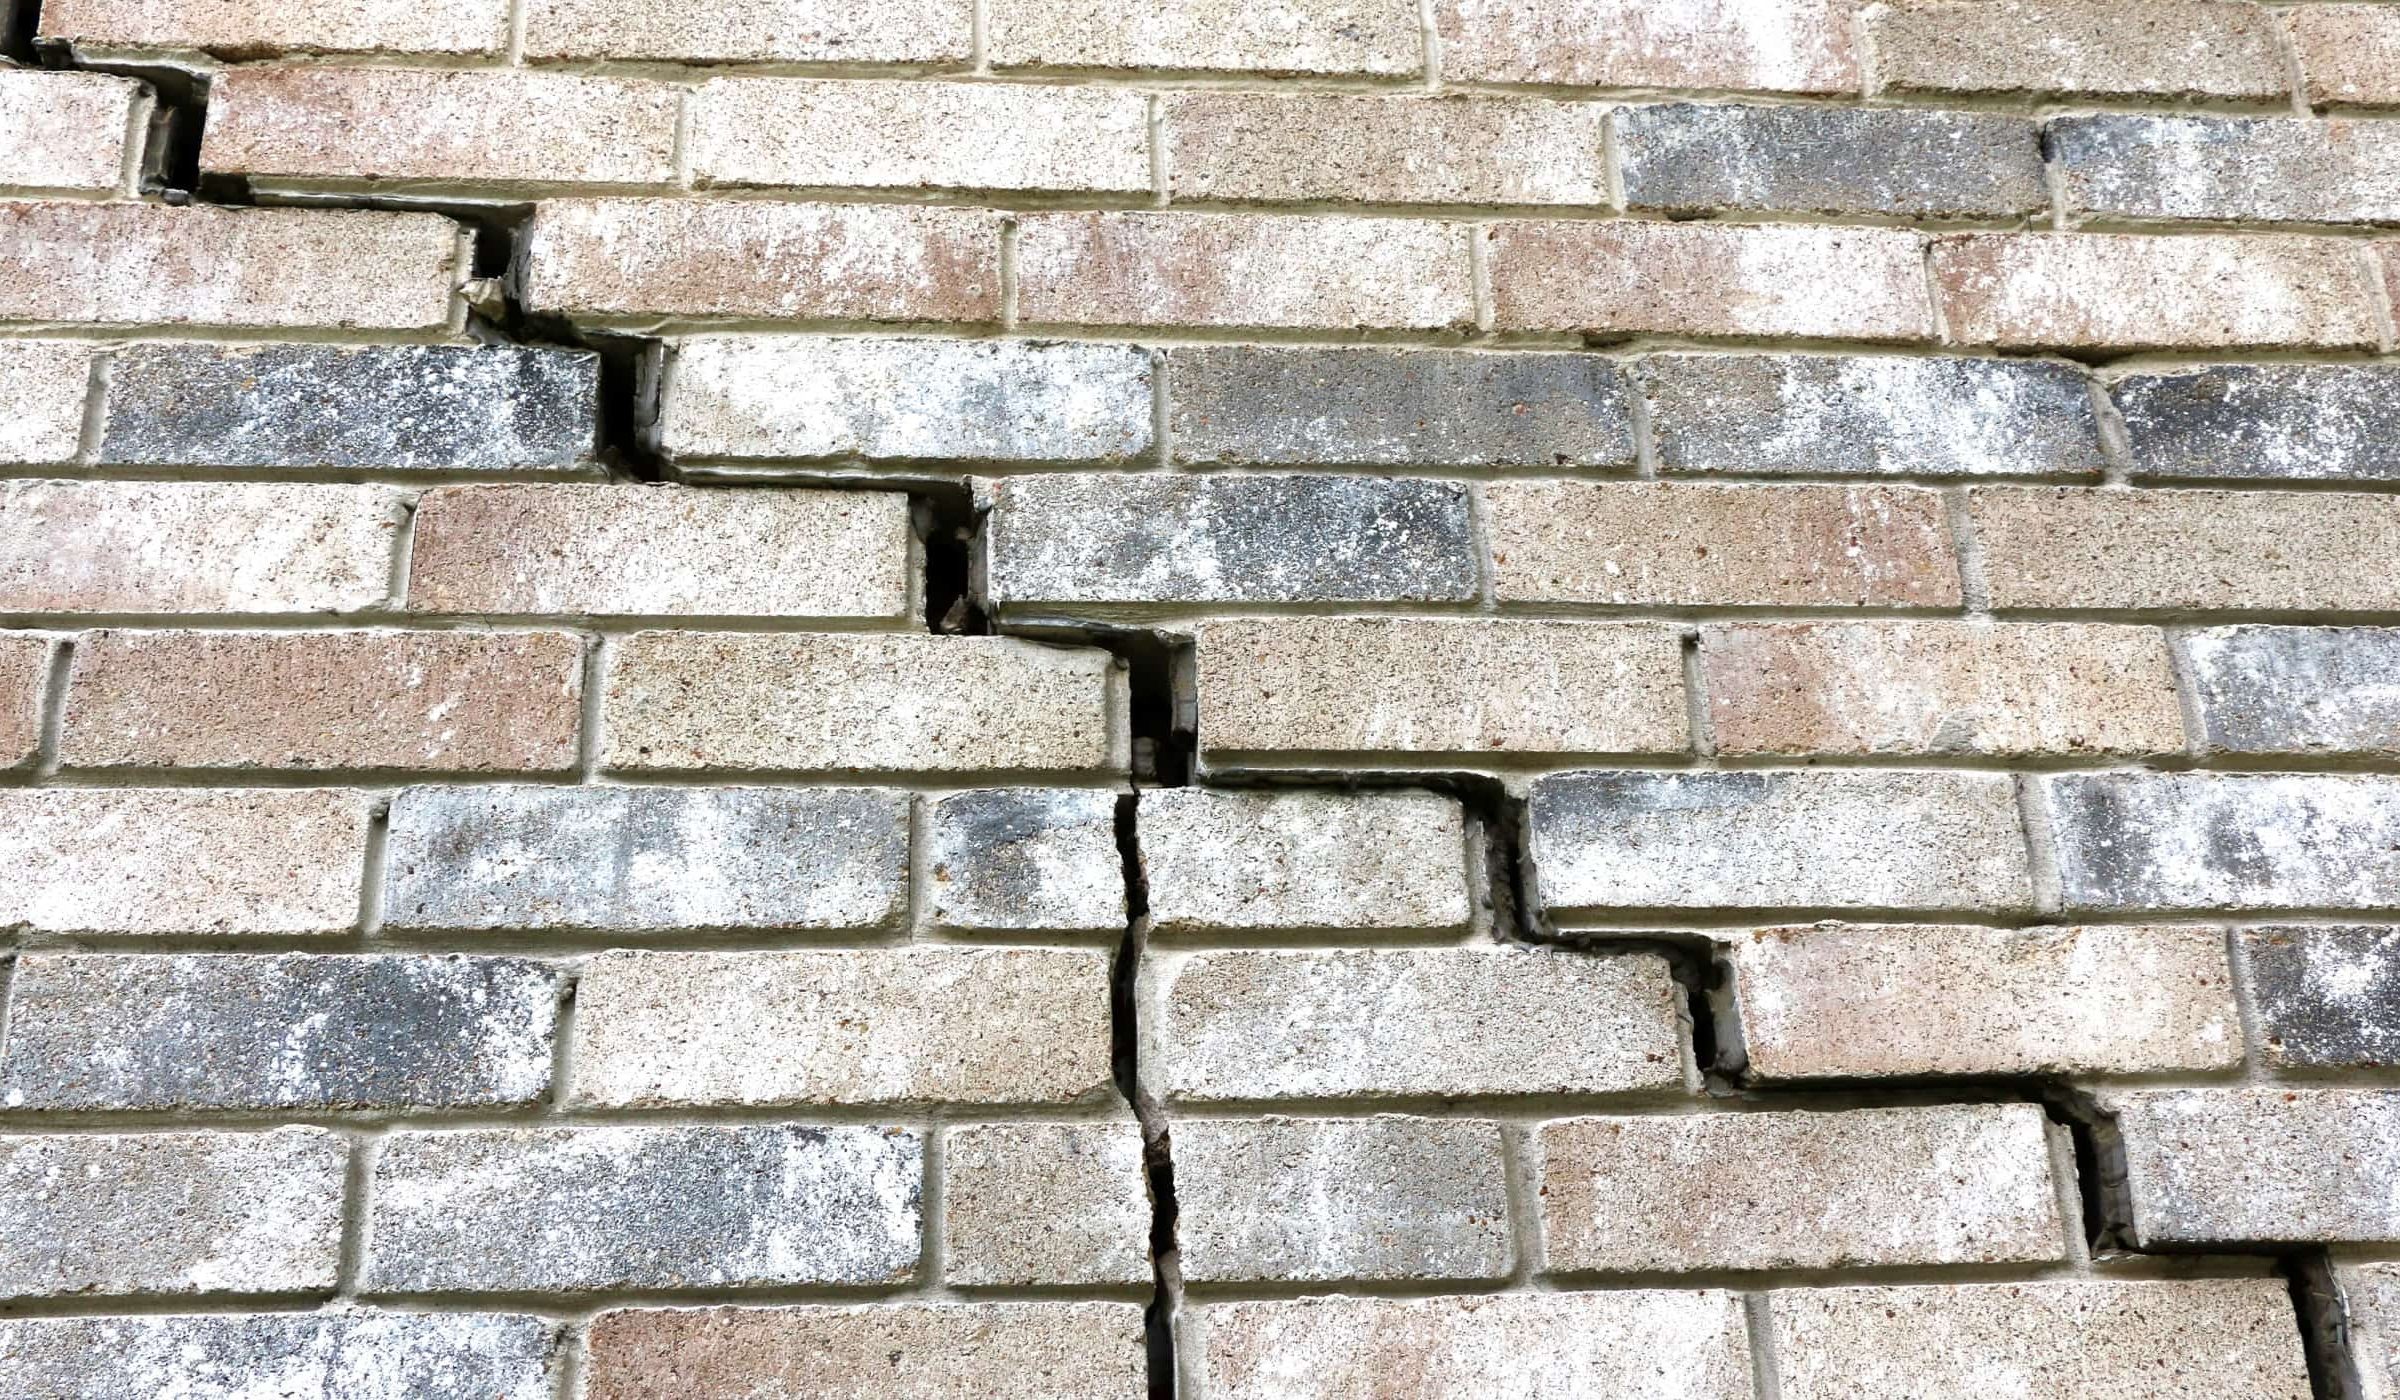
If you notice cracks in walls, uneven floors, sticking doors or windows, or other signs of structural movement, act promptly but carefully. Document all visible signs with photos and written notes before any investigation or repair work begins, and keep a record of when symptoms first appeared and how they have changed over time. Do not carry out repairs that could mask the evidence. Contact your insurer as soon as possible and ask that a structural engineer or specialist surveyor assesses the property before any work is agreed. Getting a loss assessor involved early means the evidence is protected and the claim is set up correctly from the start.

Know Your Cover
What's typically covered in subsidence insurance claims
Most home insurance policies in Ireland include subsidence cover, but it is one of the most scrutinised claim types an insurer handles. Cover typically extends to structural damage caused by movement of the ground beneath the property, including remediation, underpinning, and reinstatement of affected elements such as walls, floors, and foundations. Insurers frequently challenge the cause of the movement, the extent of the damage, and the appropriate method of repair, so professional support is particularly important. Related perils such as heave, landslip, and settlement may be covered separately or excluded depending on the policy wording, and it is important to check which applies.
Subsidence insurance claims we handle
Clay shrinkage subsidence
In Ireland's varied soil conditions, prolonged dry periods can cause clay soils to shrink and pull away from foundations, leading to structural movement and cracking that can worsen significantly over time if not addressed.
Tree root subsidence
Roots from trees and large shrubs can extract moisture from clay soils, causing shrinkage and ground movement beneath foundations, and subsidence claims involving tree roots are among the most contested due to questions of liability and maintenance.
Leaking drain subsidence
Water escaping from damaged or deteriorating underground drainage can wash away soil beneath foundations, causing localised but serious ground movement that requires both drainage repair and structural remediation.
Mining and historical ground subsidence
Properties built over historical mine workings, filled ground, or areas of known geological instability can experience subsidence unrelated to surface conditions, requiring specialist investigation and often more complex remediation solutions.
Heave and ground swelling
The upward movement of ground caused by soil expansion — often following the removal of trees or during prolonged wet periods — can cause structural damage that is distinct from subsidence but equally serious and covered under many policies.
Landslip claims
Where sloping ground moves laterally and causes structural damage to a property, landslip cover under a home insurance policy may apply, though the cause and extent of movement require careful specialist assessment and documentation.
Foundation deterioration
Ageing or inadequate foundations can contribute to structural movement over time, and while gradual deterioration may be excluded, damage caused by a sudden change in ground conditions or an identifiable event can form the basis of a valid subsidence claim.
Neighbouring works and vibration damage
Construction, excavation, or other works on neighbouring properties can destabilise ground conditions and cause structural movement to adjoining homes, creating complex liability and insurance questions that benefit significantly from professional claims support.
Structural cracking and internal damage
Beyond the primary cause of ground movement, subsidence frequently causes extensive cracking to internal and external walls, damaged plasterwork, misaligned door and window frames, and compromised decorative finishes that form a significant part of the overall claim value.
Cause & Complexity
Common causes of subsidence
The most common causes in Ireland are clay soil shrinkage during prolonged dry periods, tree root activity drawing moisture from the ground beneath foundations, leaking drains softening the soil and causing it to shift, and the natural consolidation of made-up ground or poorly compacted fill beneath older properties. Mining or extraction activity, though less common, can also cause ground movement in certain areas. Subsidence typically develops slowly, and the visible cracking or movement is often the result of a process that has been underway for some time before it becomes apparent.
Reduce Stress
Why use a loss assessor for a subsidence claim?
Subsidence claims are slow-moving, technical, and heavily scrutinised by insurers, who appoint their own structural engineers to assess the cause and scope of the damage. The insurer’s team works to protect the insurer’s position, not yours. A loss assessor works for you, commissioning independent reports where needed, reviewing the insurer’s assessments, challenging conclusions that do not reflect the true extent of the damage, and managing the process through to settlement. On a subsidence claim, professional representation can make a significant difference to both the speed of resolution and the final outcome.
Timelines
How long do subsidence insurance claims take?
Subsidence claims are often one of the longest-running types of home insurance claim. Even in a relatively straightforward case, insurers will usually need time to investigate the cause, monitor movement and confirm the right repair approach. As a result, it can take 12 to 24 months to reach an agreed outcome. More complex cases involving disputed cause, major structural damage or disagreement over repairs can take several years. Keeping detailed records from the outset, and getting expert advice early, can help support the claim and reduce unnecessary delays.

With you every step of the way

Why us for subsidence damage insurance claims support
Maximum Settlements
We’re dedicated to securing the best possible settlement for your subsidence damage claim, ensuring every aspect of your loss is fully covered and your entitlements are protected.
Subsidence Damage Negotiation Experts
With extensive experience in negotiating subsidence claims, we advocate for your rights and work to achieve a fair, timely outcome.
Full-Service Claim Management
From policy review to coordinating with structural engineers and contractors, we manage every detail of your subsidence claim, so you can focus on recovery.
Proactive and Thorough
We think outside the box to ensure every detail—from foundation shifts to hidden structural issues—is identified and comprehensively addressed.
Quick Claims Admission
We work strategically to help secure fast claim admission for your subsidence damage, minimising delays and getting restoration underway promptly.
Transparent Communication
From the initial policy review to the final settlement, we keep you informed every step of the way, ensuring a smooth, stress-free experience during a challenging time.
where we operate
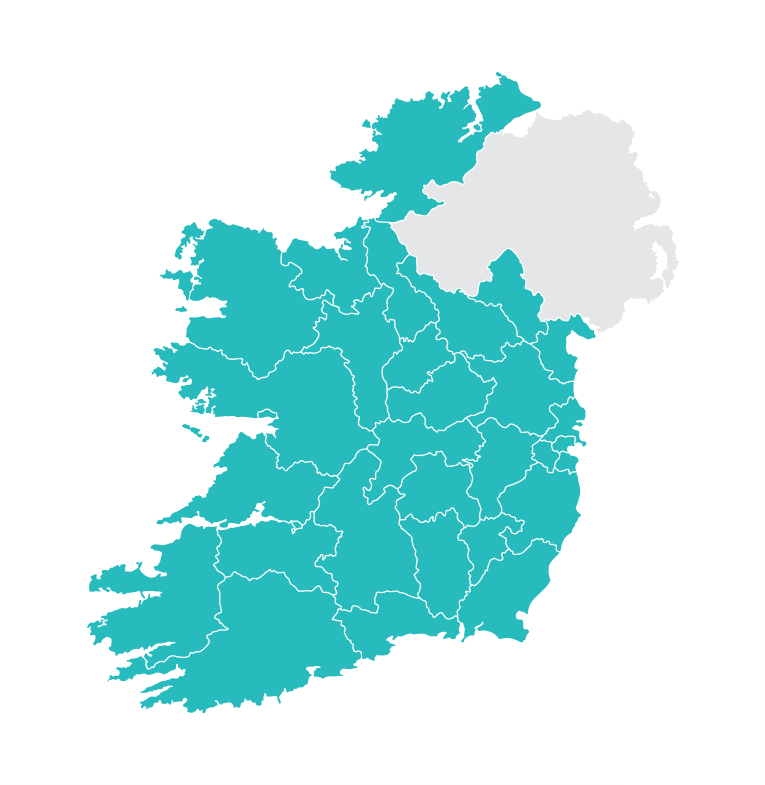
Supporting subsidence damage claims across Ireland
OMC Claims supports homeowners across Ireland with expert help on subsidence insurance claims. Whether your property is showing signs of structural movement, cracking, foundation issues, or ground instability, we can guide you through the claims process and act on your behalf, wherever you are based.
Professional memberships



Subsidence damage claim support
Subsidence insurance claim FAQs Ireland
What is subsidence and how does it affect my home?
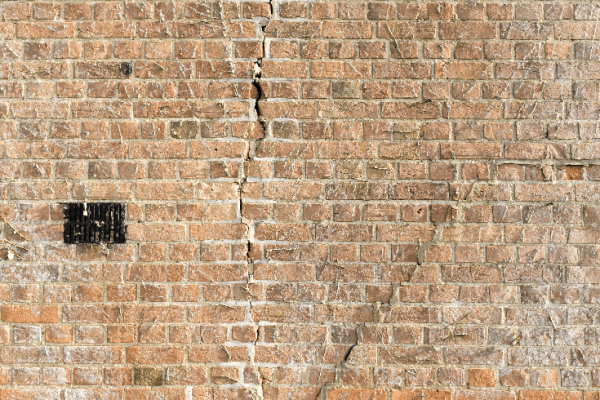
Subsidence is the downward movement of the ground beneath a property, which causes the foundations to shift and can result in cracking, structural movement, and in severe cases, significant structural damage. It is different from settlement, which is the normal, minor movement that occurs in most buildings over time. Signs of subsidence include diagonal cracks at corners of windows and doors, cracks that are wider at the top than the bottom, doors and windows sticking, and visible sloping or displacement in floors or walls. If you suspect subsidence, it is important to seek professional assessment promptly rather than waiting to see if the situation develops.
Is subsidence covered by home insurance?
Subsidence is covered under most standard Irish home insurance policies, but it is subject to a higher excess than other claim types, typically 1,000 euro or more, and insurers apply significant scrutiny to subsidence claims. Cover generally includes the cost of structural investigation, underpinning or alternative foundation repair, and reinstatement of internal and external damage caused by the movement. Whether your claim is accepted, and the level of settlement offered, depends on identifying the cause of the movement, the extent of the damage, and how well the claim is documented and presented.
What causes subsidence?
The most common causes of subsidence in Ireland are shrinkable clay soils, which expand and contract with moisture levels; tree root intrusion, where roots draw moisture from the soil and cause it to shrink; leaking drains or pipes, which can wash away sub-surface material; inadequate foundations in older properties; and in some areas, historical mining or landfill. Identifying the specific cause is critical to both the repair solution and the insurance claim. Insurers need to understand the cause before they will agree to fund remediation.
How do I know if my cracks are caused by subsidence?
Not all cracks indicate subsidence. Hairline cracks in plaster are common and usually the result of normal thermal movement or drying shrinkage. Cracks that suggest subsidence are typically diagonal rather than vertical or horizontal, wider at one end than the other, appear at structural junctions such as corners of windows and door frames, and progress over time. If you have cracks that are widening, recurring after repair, or accompanied by sticking doors or sloping floors, you should have the property professionally assessed. A loss assessor can help coordinate the right specialist surveys.
What is the difference between subsidence, settlement, and heave?
Subsidence is downward ground movement beneath a property. Settlement is the gradual, minor compaction that occurs in most buildings and is generally not covered by insurance. Heave is the upward movement of ground, typically caused by clay soils absorbing water after a tree root source is removed, and is treated differently to subsidence in most policies. Understanding which type of movement is occurring matters for both the repair approach and the insurance claim. An independent structural engineer’s report is usually required to establish this definitively.
What should I do if I suspect subsidence?
Document any cracks or movement with dated photographs. Try to note when the cracking first appeared and whether it has changed over time. Do not carry out repairs to cracked areas before having the property assessed, as this removes the evidence your insurer needs. Contact your insurer to notify them of the potential claim. Before your insurer’s loss adjuster visits, consider speaking to a loss assessor. This ensures you have independent advice before any assessments or recommendations are made on your behalf.
How much does it cost to fix subsidence?
The cost of subsidence repair varies enormously depending on the cause, the extent of the movement, and the repair method required. Underpinning a single section of foundation can cost from 10,000 to 30,000 euro or more; whole-house underpinning can run to six figures. Alternative methods such as resin injection or helical piers may cost less in suitable cases. Where drainage is the cause, pipe repair may resolve the issue without major structural intervention. Your insurance policy should fund the repair up to your sum insured, less the applicable excess. Having an independent assessment of the repair scope ensures you are not accepting an insurer-appointed solution that undervalues the work needed.
Will a subsidence claim affect my home insurance in future?
A subsidence claim can affect your future insurance premiums and in some cases your ability to obtain cover on standard terms. Insurers view subsidence as an ongoing risk once it has occurred. However, the impact depends on whether the cause has been fully remediated, whether a structural engineer has confirmed the property is stable, and what documentation exists to support this. It is worth understanding the long-term implications before lodging a claim, particularly for lower-value cases where the damage may be within or close to the excess level.
How long does a subsidence insurance claim take to settle?
Subsidence claims often take longer than most other home insurance claims because the insurer usually needs to investigate the cause and monitor movement before repairs can be agreed. In many cases, the process takes 12 to 24 months, while more complex or disputed claims can continue for several years.
How much does a loss assessor cost for a subsidence claim?
Our fee for subsidence claims is typically 10% plus VAT of the final settlement, agreed in advance. Given the complexity of subsidence claims, the length of the process, and the significant sums involved, professional representation is particularly important. Subsidence claims require coordination of multiple specialists, careful management of the insurer’s investigation process, and rigorous scrutiny of repair scopes and settlement offers. The difference between a well-managed and a poorly managed subsidence claim can be substantial. Your first consultation with OMC Claims is free.
If your question is not covered in the FAQs above, please do not hesitate to contact us.
Preferred partner for Ireland’s top Insurance Brokers