Can I Claim on Home Insurance for a Leaking Roof?

 By Jim Flannery ACII, Brand Ambassador, OMC Claims. Over 40 years in insurance claims and a founding member of the Irish Claims Consultants Association.
Summary
A leaking roof is covered by home insurance in Ireland when the leak was caused by a sudden, insured event, most often storm damage, a fallen tree or accidental damage. Leaks caused by wear and tear, gradual deterioration or poor maintenance are not covered. Where the cause was insured, the claim usually extends to the resulting internal damage, including ceilings, decoration and belongings. Flat roofs often carry specific age and maintenance conditions, and if the insurer refuses to pay, the decision can be challenged.
A leaking roof rarely announces itself politely. A stain on the ceiling, a drip during heavy rain, and suddenly you are wondering what the repair will cost and whether the insurance will pay. The answer depends almost entirely on what caused the leak. If water is already through and damaging the house, our team provides water damage claims support alongside the roof question itself.
This guide covers everything: the causes and signs of roof leaks, how weather events affect claims, what your policy covers, the flat roof rules, the claims process and documentation, what to do if the insurer says no, and how to prevent the next one.
In this guide
- › Does home insurance cover a leaking roof?
- › What causes a roof leak?
- › Signs your roof is leaking
- › The role of weather events in roof leak claims
- › Understanding the impact of roof leak damage
- › Accurate disclosure when taking out cover
- › Types of roof leak damage covered
- › Flat roof considerations
- › Temporary repairs versus permanent fixes
- › Immediate steps after discovering a leak
- › How to make a roof leak claim
- › What documentation you need
- › Mistakes to avoid
- › When to hire a loss assessor
- › Will a claim affect my no-claims bonus?
- › What to do if your claim is denied
- › How long does a claim take to settle?
- › Preventing roof leaks in the future
- › If you cannot live in your home
Does home insurance cover a leaking roof?
Yes, when the leak was caused by a sudden and unforeseen insured event. Storm damage is the classic case: wind strips slates or lifts flashing, and rain follows through the opening. Fallen trees, unexpected structural failures and genuine accidental damage sit in the same category. To qualify, you need to show the leak resulted from an unexpected incident rather than ongoing deterioration.
No, when the leak results from wear and tear. Roofing materials age under constant exposure to sun, wind and rain, and gradual deterioration, poor maintenance or neglect are the homeowner’s responsibility, not insured events. A claim for an old flat roof that is sagging, with water pooling, or evidence of previous patch repairs is highly likely to be declined. If the insurer judges the leak was down to a roof that had simply worn out, the claim will be refused.
Cover details vary significantly between insurers, so review your policy’s terms, exclusions, limits and any maintenance or inspection requirements. This single distinction, sudden versus gradual, decides most roof leak claims.
What causes a roof leak?
Recognising the root cause matters, because it largely determines whether the policy responds:
-
Weather damage: heavy rain, storms and strong winds, familiar Irish conditions, dislodging tiles and damaging the structure. These sudden events are often covered, provided the damage was not down to pre-existing weakness
-
Wear and tear: gradual degradation from UV, wind and rain producing small cracks and gaps over time. Typically not covered, as it is a maintenance matter
-
Blocked gutters and roof valleys forcing water under the roofline
-
Impact: fallen trees, branches and debris
-
Workmanship failures following recent roof work
Where a storm is the cause, the roof claim and the storm damage insurance claim are two parts of the same event, and the evidence for one supports the other.
Signs your roof is leaking
Learning the signs saves time and money, because early action limits the damage:
-
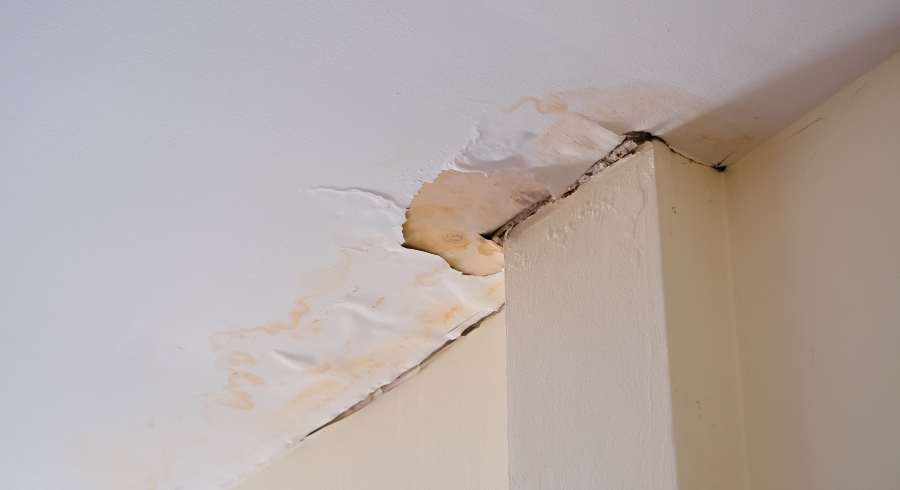
Water stains on ceilings or walls: discoloured, often yellowish-brown patches or rings that grow while the leak persists
-
Damp or musty odours, particularly in the attic or between walls, usually meaning mould or mildew is already growing
-
Peeling paint or wallpaper: moisture causing paint to bubble and blister and wallpaper to loosen, a sign of water behind the surface
-
Mould or mildew growth on ceilings, upper walls or corners, which damages the home and carries real health risks
-
Dripping water during rainfall: the definitive, urgent sign that immediate action is needed
The role of weather events in roof leak claims
Ireland’s weather drives most roof leaks, but insurers do not treat all weather-related leaks equally, so it pays to know what qualifies.
Storm damage is the strongest ground: strong winds and heavy rain displacing tiles, damaging flashing or tearing off sections of roof. Most Irish policies cover storm-related roof damage, though some specify a minimum wind speed in the wording, and the damage must be sudden and unforeseen. Heavy rainfall alone is more contested: intense rain exploiting existing cracks or gaps may be covered where the damage is sudden, but where the leak traces to poor maintenance the claim is at risk. Hail and ice are less common here but can puncture materials, and ice dams at the roof edge can push water back under slates; cover depends on your specific terms. Fallen trees and debris are generally covered when linked to a storm, with one caveat: if the tree was already dead or diseased, the insurer may argue negligence.
Understanding the impact of roof leak damage
A roof leak reaches well beyond the visible stain. Water intrusion weakens ceilings, damaging insulation, wall plaster and support timbers, rotting wood, crumbling drywall and rusting metal components into expensive structural repairs. Where water meets electrics, the risks step up: short circuits, electrical fires and shock hazards, which is why power to affected areas should be switched off and any compromised wiring, sockets, switches or light-fittings inspected by an electrician. Persistent damp feeds mould and mildew, with respiratory and allergy consequences, and mould spreads fast through walls, ceilings and ventilation. And costs compound: a small patch of water damage left alone becomes structural repair, mould remediation and, in the worst cases, full roof replacement.
Accurate disclosure when taking out cover
One issue surfaces at claim time that actually begins when the policy is bought. Insurers assess risk on the information you provide, so disclose the roof’s type, age, materials, condition and any previous repairs accurately when obtaining quotes. Discrepancies or omissions, intentional or not, can lead to a denied claim or an invalidated policy. Complete, honest detail at the outset prevents exactly the dispute you do not want mid-claim. A timber and felt flat roof extension will be calculated based on it’s percentage to the overall roof area. A thatched roof is a specialist high risk proposition, limiting the number of insurers who will even consider insuring.
Types of roof leak damage covered
Where the cause was insured, the claim can be broader than many homeowners expect:
-
Damage to ceilings, walls and floors: repainting, replacing plasterboard and fixing water-damaged flooring
-
Roof repairs: replacing missing tiles, repairing flashing and addressing structural damage to the affected section
-
Personal property: furniture, carpets, bedding, electronics and belongings damaged by the leak, documented with photographs and receipts
-
Temporary accommodation: where severe damage makes the home uninhabitable while repairs are completed
Ceiling damage is often the larger cost, and our guide to ceiling water damage claims covers that element in detail. The wider internal loss is handled through our water damage insurance claim support.
Flat roof considerations
Flat roofs get special treatment from insurers, and homeowners with one, even on an extension, should know the rules.
The underlying issue is water pooling: flat roofs do not shed water like pitched ones, so inadequate falls or blocked drainage leads to standing water, leaks and structural damage, and many insurers require proof of regular maintenance of the drainage. Flat roofs also have shorter lifespans, and some policies restrict or exclude cover once the covering passes a stated age, often somewhere between 7 and 20 years, or where it has not been maintained. Materials matter too: felt, rubber membrane and asphalt vary in durability, and the roof should meet building regulations to avoid disputes. Premiums can run higher for flat-roofed homes, though evidence of proper maintenance, such as annual inspections, helps on both price and claim approval.
When claiming for flat roof damage after a storm or heavy rain, the process is the same as any roof claim, but expect closer scrutiny, particularly where wear or maintenance might be argued. Regular professional inspections, clear drainage and a written maintenance record are the strongest counters.
Temporary repairs versus permanent fixes
Insurers expect you to prevent further damage, so emergency measures such as tarping the roof or sealing a leak are appropriate, and policies often cover the cost. These quick fixes protect the home from further damage until permanent repairs are agreed.
Permanent repairs are different. Where the leak flows from a covered event, the policy typically pays for the proper fix, replacing damaged materials, tiles or flashing, but get the insurer’s approval before extensive work begins. Premature permanent repairs can leave you unable to prove the cause, and you may be accused of prejudicing your own position. Keep receipts and records for every repair, temporary or permanent, both for reimbursement and to substantiate the claim.
Water coming through the roof right now?
Make it safe, photograph everything, and talk to us before permanent repairs. We prepare and negotiate the claim on your behalf. The first conversation is free and carries no obligation.
Immediate steps after discovering a leak
-
Ensure safety first: if water is near electrical outlets or appliances, turn off electricity to the affected area, and avoid standing water around electrics
-
Limit the damage: move furniture, electronics and belongings clear, catch drips in containers, and protect floors with towels or plastic sheeting
-
Document the damage: take clear photographs and video from multiple angles, close-ups and wide shots, before anything is moved or repaired
-
Notify your insurer as soon as possible with preliminary details, and follow their instructions on next steps
-
Arrange temporary repairs if safe, such as a tarpaulin over the damaged section, keeping all receipts for reimbursement
How to make a roof leak claim
The claims process runs through five stages, and knowing them in advance keeps it manageable.
Initial contact: report the leak with the first details and, ideally, speak to a loss assessor at this point about how to present the case from the outset. Assessment: the insurer assigns an adjuster to inspect the damage, establish the cause and confirm whether the policy responds; an assessor can attend that inspection to make sure every element of damage is identified and the evaluation is fair and complete. Documentation: submit photographs, a detailed statement of claim, repair estimates, receipts and a written account of the event, organised to show the full extent of the loss. Approval: the insurer reviews the adjuster’s report and may come back with questions, which professional representation handles efficiently. Settlement and repairs: funds are agreed and released, the settlement is checked against the true cost and scope of repairs, negotiated further if it falls short, and contractors then complete the work, with receipts kept for final reconciliation.
What documentation you need
-
Photographs and video of the damage from multiple angles, including close-ups of the leak, wider context shots and any damaged belongings
-
Detailed written repair estimates from reputable, licensed contractors, with a breakdown of work and costs. A roofer’s report on the mechanism of damage is especially valuable: “wind-lifted flashing on the night of the storm” wins claims where “roof needs work” loses them
-
A detailed inventory of damaged contents with replacement estimates
-
Receipts for any emergency or temporary repairs carried out to prevent further damage
-
A copy of your insurance policy, for reference to the specific terms, conditions and cover
-
A clear written account of how and when the leak occurred, including weather conditions and events leading up to it
Mistakes to avoid
-
Delaying the claim notification: prompt reporting demonstrates diligence and prevents the argument that further damage was down to neglect
-
Thin documentation: capture the damage comprehensively, including before-and-after shots where temporary repairs are made
-
Permanent repairs before assessment: protective fixes are necessary, but permanent work before the adjuster’s inspection invites disputes over cause and extent
-
Not reading the fine print: exclusions and limitations apply to roof cover more than most, so know what your policy actually says
-
Underestimating professional representation: complex claims presented alone tend to underpay, whereas an assessor makes sure the claim reflects the full loss
When to hire a loss assessor
Not every leak needs professional representation, but three situations justify it. Extensive or complicated damage, where the leak has affected the structure or multiple parts of the home, benefits from professional documentation of the full extent. A denied or undervalued claim is the second: an assessor can build the appeal or negotiate a settlement that actually covers the damage. And plain uncertainty is the third: if the process is unfamiliar, an assessor guides each step, keeps the documentation complete and the deadlines met. An assessor can remove the uncertainty and stress of dealing with the unknown and can restore confidence while the negotiations are progressing
Will a claim affect my no-claims bonus?
It can, and it is worth weighing before you file. A claim may reduce or remove a no-claims bonus, and insurers often treat claims as an indicator of risk at renewal, so premiums can rise even where the claim was approved. The calculation is straightforward enough: for minor damage close to your excess, absorbing the cost may make sense, while for significant damage the repair bill almost always outweighs the premium impact. Make it a decision rather than an accident.
What to do if your claim is denied
A refusal is not the end of the road. Start by requesting a written explanation of exactly why the claim was declined, which identifies the ground you need to challenge. Gather additional evidence against it: weather records for the date, photographs of the roof before and after, maintenance history, and expert opinions from contractors or an independent assessment. Then use the insurer’s formal appeals process, submitting the new information and requesting a re-evaluation.
If the appeal fails, you can escalate to the Financial Services and Pensions Ombudsman, which provides free, impartial dispute resolution between consumers and financial service providers in Ireland. Refusals on roof claims almost always rest on wear and tear, and where the evidence supports a sudden cause, that argument is very challengeable.
How long does a claim take to settle?
Timelines vary with the complexity of the damage and the responsiveness of everyone involved. Straightforward claims with clear documentation and minor damage can settle within a few weeks. Complex claims, involving extensive damage, coverage disputes or multiple assessments, can run several months, particularly where appeals or expert opinions are needed. The insurer’s internal processes, contractor availability and the thoroughness of your documentation all influence the pace, which is one more reason why a complete file from day one pays for itself.
Preventing roof leaks in the future
A well-maintained roof lasts longer, costs less and strengthens any future claim. The habits that matter:
-
Inspect the roof at least twice a year, in spring and autumn, checking for missing, cracked or curled roofing felt, damaged flashing, moss and algae, and staining in the attic or on ceilings
-
Clean gutters and downspouts regularly, especially in autumn, direct downpipes away from the foundation, consider gutter guards, and watch for rust, cracks and separations
-
Trim overhanging branches so falling limbs cannot puncture the roof or clog the gutters, using a professional arborist for large trees near the house
-
Ensure proper roof ventilation: clear attic vents, working ridge and soffit vents, and a dry attic, since trapped moisture weakens materials and feeds mould
-
Address minor repairs promptly: replace loose or missing tiles immediately, and check the flashing and caulking around vents, chimneys and skylights for small cracks
-
Consider a waterproof membrane beneath the roofing materials, particularly valuable in wet climates, adding a barrier against seepage
-
Schedule professional maintenance every few years, so hidden issues are found and fixed before they cause damage
-
Give flat roofs extra care: correct slope and drainage, inspections after heavy rain for pooling, and a protective coating to enhance waterproofing
If you cannot live in your home
In severe cases a roof leak makes the home uninhabitable. Many policies include temporary accommodation cover for hotel stays, short-term rentals or other arrangements while repairs are made. Review your policy for the limits on amount and duration, coordinate the arrangements with your insurer in advance, and document every expense for reimbursement.
Expert view
“Roof claims are won and lost on the roofer's report. A quote that says the roof needs replacing tells the insurer it was worn out. A report that says the flashing was lifted by wind on the night of the storm tells them it is a claim. Same roof, same damage, very different outcome.”
Jim Flannery ACII, Brand Ambassador, OMC Claims
Frequently asked questions
Does insurance cover roof leaks from poor maintenance?
No. Damage caused by neglect or lack of maintenance is excluded, which is why regular inspections and upkeep matter both for the roof and for any future claim.
Will insurance cover mould caused by a roof leak?
Yes, where the mould results directly from a covered event such as a storm-induced leak. Pre-existing mould problems are usually not covered.
Can I claim for personal belongings damaged by a roof leak?
Yes, most policies cover personal property damaged by a covered leak. Document every affected item and provide estimates or receipts where possible.
Do I need to pay an excess on roof leak claims?
Yes, most policies apply an excess, a predetermined amount deducted from the claim payout. Check your schedule for the figure.
Can I choose my own contractor for repairs?
Yes, provided they are licensed and insured. Your insurer may also offer a list of approved contractors.
How do I know if my roof leak is covered?
Check the covered perils in your policy. Leaks caused by sudden events such as storms are typically covered, while gradual wear and tear is not. Your insurer or a loss assessor can clarify your specific position.
Does house insurance cover roof repairs?
Yes, where the damage was caused by an insured event such as a storm, a fallen tree or accidental damage. Repairs arising from wear and tear, poor maintenance or gradual deterioration are not covered, and the policy pays to repair the damaged section rather than to upgrade the roof.
Does house insurance cover broken roof tiles?
Yes, if the tiles were broken by an insured event such as storm winds or a falling branch. Tiles that have cracked, slipped or deteriorated through age and weathering count as wear and tear and are excluded, which is why insurers ask when the damage first appeared.
How do I get insurance to pay for a roof replacement?
Full replacement is normally only paid where an insured event has damaged the roof beyond economic repair. Strong evidence is essential: photographs, a roofer’s or engineer’s report confirming the cause, and maintenance records. If the insurer offers a partial repair you believe is inadequate, a loss assessor can independently value the work and challenge the scope.
Will insurance cover a 20-year-old roof?
Usually, for sudden insured damage, though expect closer scrutiny. Some policies restrict cover once a flat roof passes a stated age, or where it has not been adequately maintained. Evidence of regular inspections and prompt minor repairs strengthens both the claim and your position if the cause is disputed.
What if the insurance payout is not enough to cover the repairs?
You can negotiate with the insurer or engage a loss assessor to advocate on your behalf and make the case that the settlement should reflect the true cost of the necessary repairs.
How long do I have to file a roof leak claim?
Policies set specific timeframes for reporting damage, and they vary. Report as soon as possible after discovery to avoid complications or denial.
Will a roof leak claim affect my no-claims bonus?
It can reduce or remove the bonus and may affect your premium at renewal. For minor damage close to the excess, weigh the claim against the likely premium impact.
If your roof is leaking, the sequence is simple: make it safe, photograph everything, and establish the cause before anyone mentions wear and tear. OMC Claims acts only for policyholders, across all 26 counties. Contact us for a free, no-obligation conversation.
About OMC Claims
OMC Claims (Owens McCarthy Ltd) is Ireland’s largest independent firm of loss assessors, acting only for policyholders, never for insurers. We provide nationwide coverage, with loss assessors serving Dublin, Cork, Limerick and every other county in Ireland. Part of the Fexco group and regulated by the Central Bank of Ireland (Registration Number C-46734), our team brings over 250 years of combined claims experience and handles more than 2,000 home and business claims a year, from straightforward domestic losses to large and complex commercial claims. We assess the damage, prepare and value your claim, and negotiate with your insurer to work to secure the settlement you are entitled to.
Disclaimer: This content is for general informational purposes only and aims to provide an overview of roof leak insurance claims. It does not constitute legal, financial, or insurance advice. For guidance tailored to your specific circumstances, please consult a claims professional or your insurance broker/provider.